Jiajing Sun, PhD, CFA, FIMA
Associate Professor and Deputy Director, Department of Statistics and Data Science, School of Economics and Management, University of Chinese Academy of Sciences (UCAS), Beijing. She holds a PhD in Management from the University of Liverpool, with a specialisation in econometrics. A CFA charterholder since 2013, she is also a Fellow of the Institute of Mathematics and its Applications.
Editorial appointments and professional affiliations
Associate Editor · The Review of Mathematical Economics · Digital Finance · Management & Marketing
Member, Institute for Digital Assets (IDA); Fellow, Institute of Mathematics and its Applications (FIMA); Member, London Mathematical Society. CFA charterholder credential
Featured research and software | Affine-Equivariant Adjusted-Range Self-Normalization
Changing units or reordering coefficients should give the same inference about the underlying economic quantities. Yongmiao Hong, Zhuo Lin, Oliver Linton, Whitney K. Newey and Jiajing Sun develop joint confidence regions for dependent time series without estimating a long-run covariance matrix or choosing a bandwidth. Their application studies US fiscal multipliers. The paper appears in the University of Cambridge Janeway Institute working paper series (No. 2637).
Jiajing Sun co-authors and maintains aersn, the R and Python implementations of the method.
Cambridge working paper · R package (CRAN) · Python package (PyPI) · Method and confidence-region animations
Financial econometrics and risk monitoring
Dr Sun studies how to distinguish a lasting change in economic relationships from the fluctuations that occur as new observations arrive. With collaborators, she develops adjusted-range self-normalisation methods for inference with dependent data. Her work covers tests for structural breaks, the stability of functional time series, and online monitoring of risk signals in options markets. Her methodological research has appeared in the Journal of Econometrics, Economics Letters and Statistical Research. She has led projects funded by the National Natural Science Foundation of China, including a General Program project on adjusted-range self-normalisation in time series analysis.
Her applied work includes research with the China Financial Futures Exchange on early warning of risks in derivatives markets. In digital finance, she and her collaborators used text analysis and machine learning to assess the digital financial competitiveness of 541 small and medium-sized Chinese banks. In ecological economics, they traced virtual water through international supply chains, distinguishing reliance on rainfall from surface-water and groundwater withdrawals and from the pressure associated with water pollution. This research appeared in Ecological Economics.
Investment practice and public commentary
On 29 October 2026, Dr Sun moderated “Technology Investing: Revaluation or Overinvestment?” at the 9th CFA Institute China Investment Conference in Beijing. The panel brought together perspectives from investment management, the technology industry and academia to examine when higher valuations reflect a change in a business’s prospects and when rapid expansion may signal overinvestment. Earlier that month, she contributed expert commentary to CFA Institute on reform of China’s capital markets and China’s role in the clean energy transition. She discussed the implications of corporate governance for long-term returns and why growth in a clean energy industry need not translate into comparable returns for investors.
Postgraduate teaching and academic service
Dr Sun teaches financial econometrics, advanced time series analysis and financial data modelling. In her courses, students use real economic and financial data to connect the assumptions behind a statistical method with the results it produces. They reproduce analyses in R and Python, compare forecasts and examine why models perform differently. Her course Financial Statistics and Econometrics received the School’s Special Teaching Award for Young Teachers in the 2017–2018 academic year and an Excellent Graduate Course Award in 2019. Modelling and Analysis of Financial Data received an Excellent Graduate Course Award in 2022. In July 2026, she took part in Harvard Business School’s Global Colloquium on Participant-Centered Learning.
Her textbooks and companion resources cover financial econometrics, time series methods, FinTech, applied econometrics and regression. The companion sites provide chapter guides, lecture slides, videos and coding exercises. With Per Johansson, she is writing Regression with R and Python: Description, Prediction, and Causal Analysis in Social Science and Medicine, forthcoming from Springer in 2027. The accompanying course is available on Quantinar.
Previously Deputy Director of the School’s International Cooperation Office, Dr Sun helped develop ties with the Energy Studies Institute at the National University of Singapore. She organised the 2022 and 2023 Asian Summer Schools in Econometrics and Statistics and contributed to the organisation of the 2026 summer school.
Academic website and teaching resources: https://jiajing-sun.com/
Email: jiajing@ucas.ac.cn
Postal address: No. 3 Zhongguancun Nanyitiao, Haidian District, Beijing 100190, China.
Research Areas
Econometrics, Statistics, and Economics.
Education
Dr Sun participated in the Global Colloquium on Participant-Centered Learning, a faculty development programme on case-method teaching, leading classroom discussions, curriculum design and case development. View programme certificate
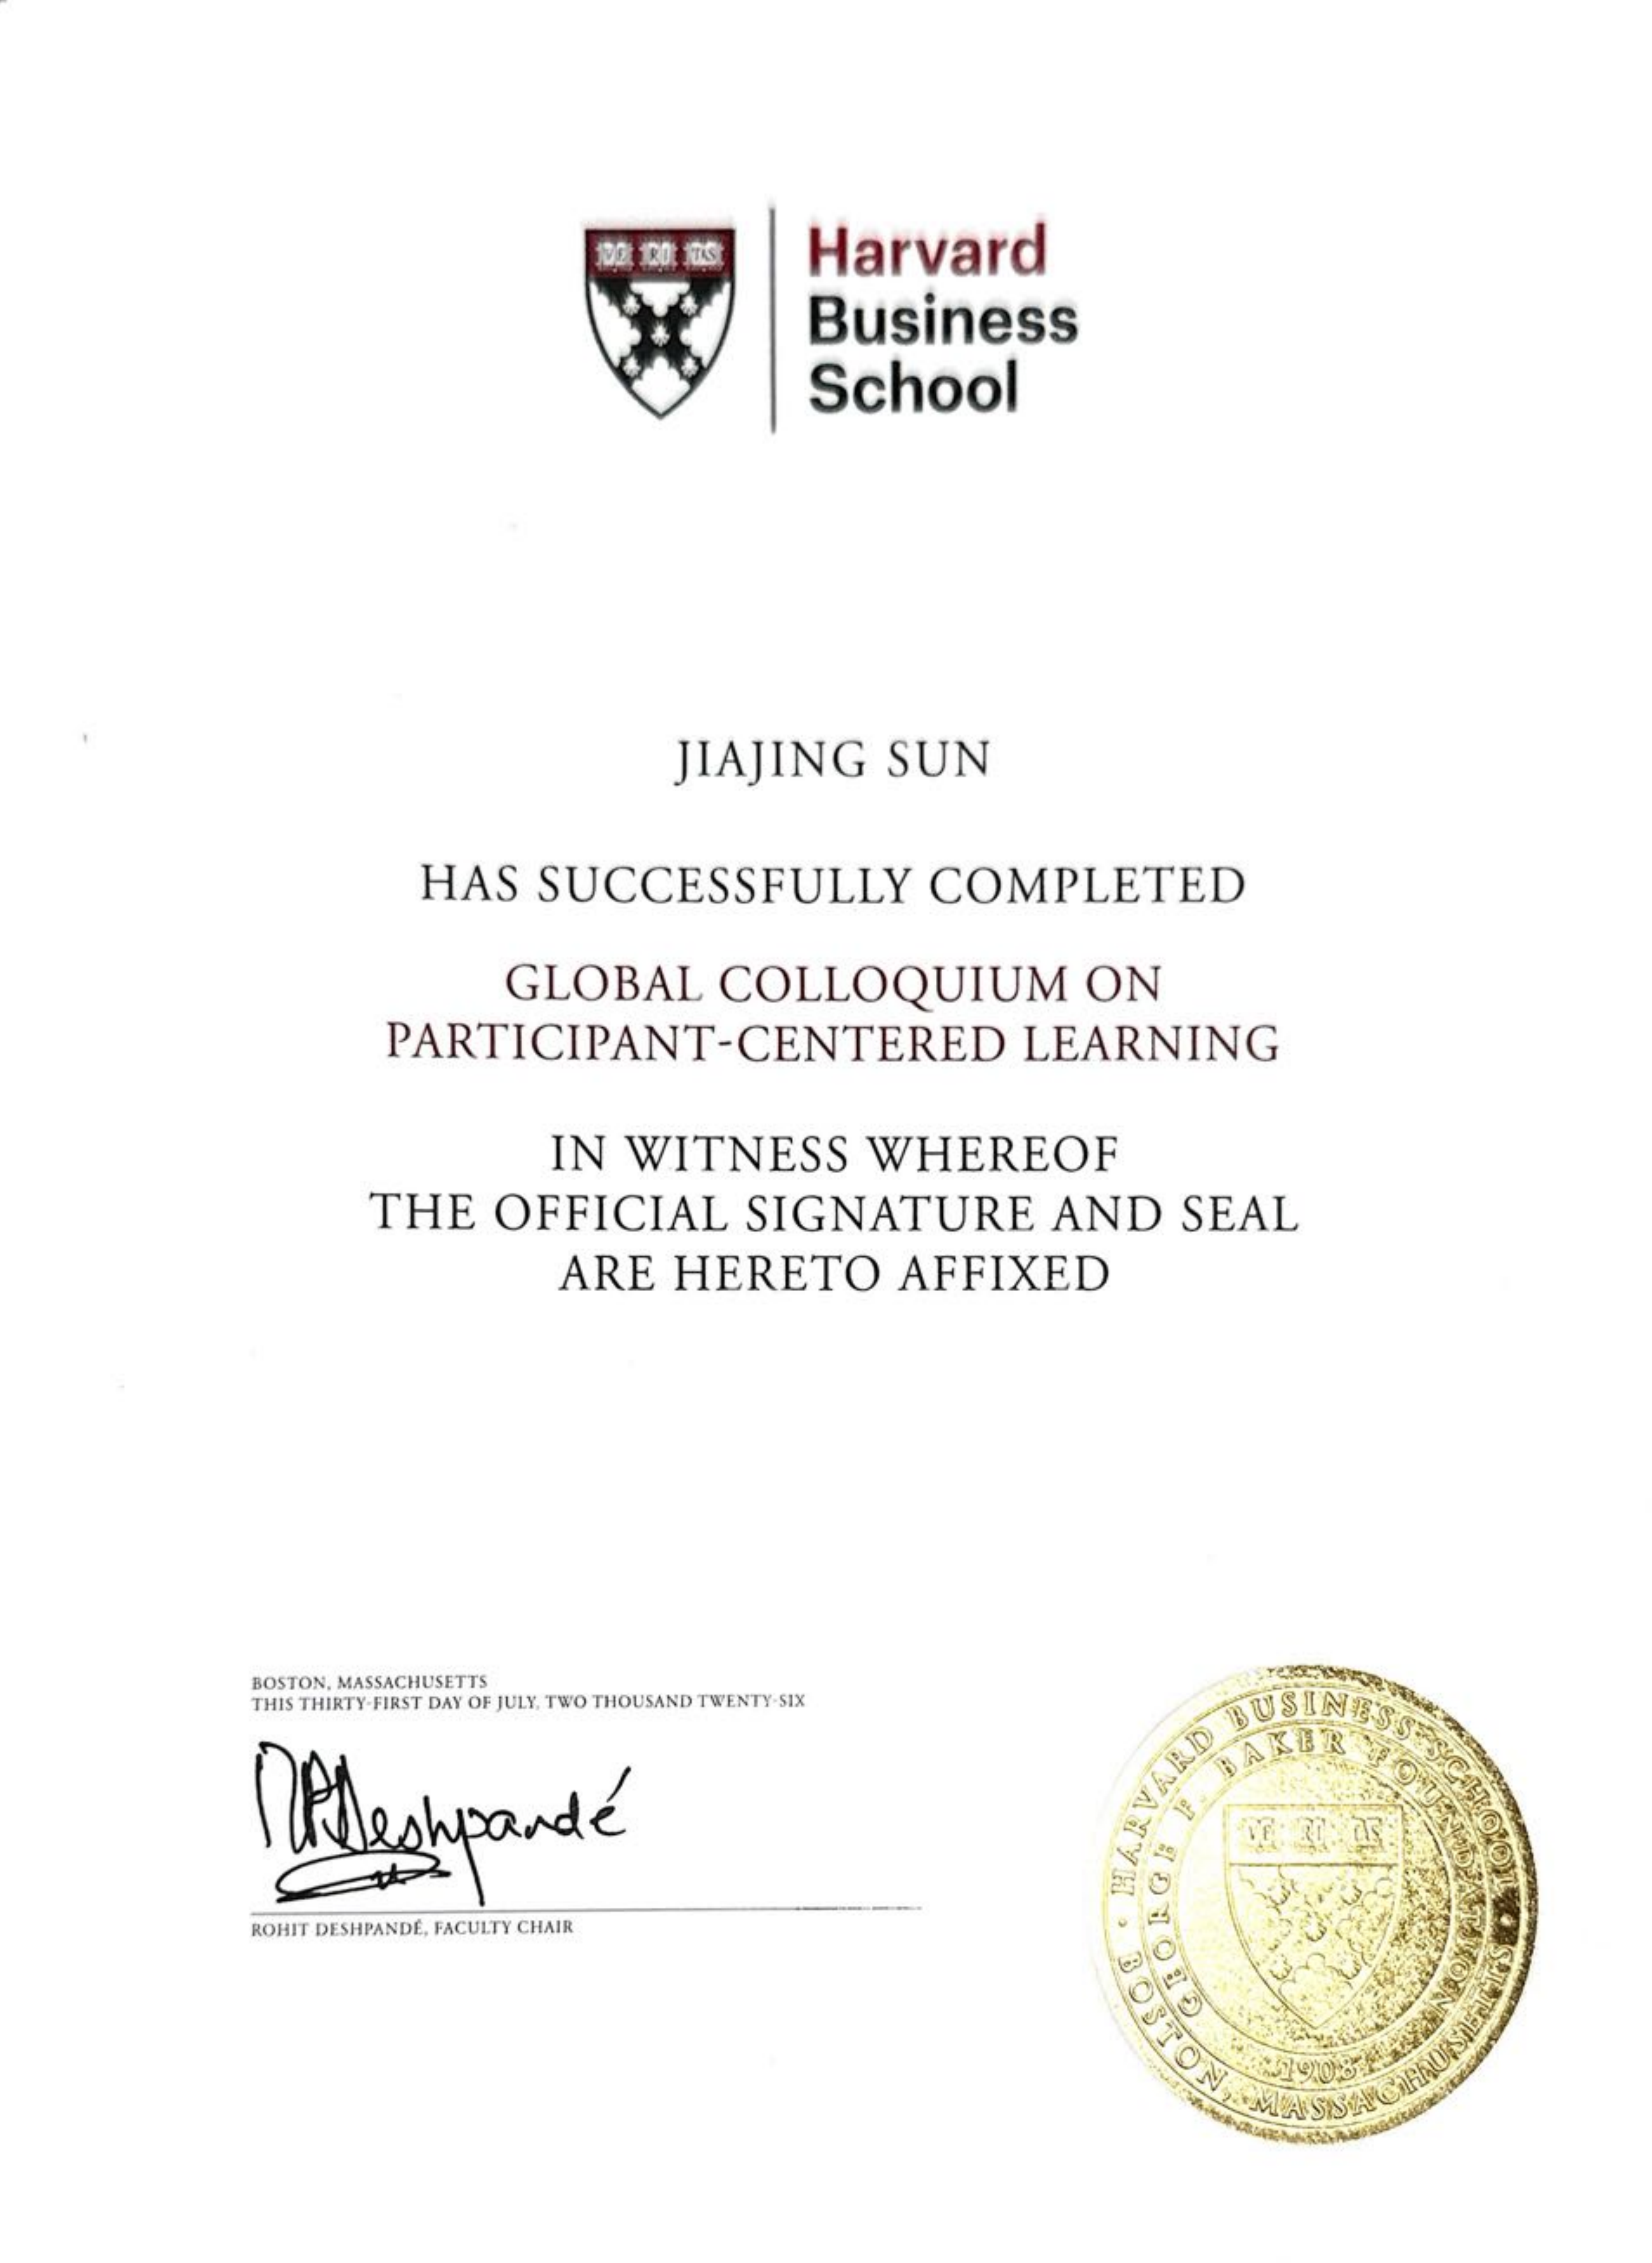
Harvard Business School Executive Education · Boston, Massachusetts · 26–31 July 2026.
Faculty development
- October 2007 - July 2011, Management School, University of Liverpool, PhD Management Studies (Econometrics).
- September 2004 - November 2005, College of Humanities and Social Science, University of Edinburgh, MSc in Economics.
- September 2001 - July 2004, Tianjin University of Finance and Economics, Bachelor's Economics (I finished four years undergraduate programme within three years).
Publications
Research publications and book chapters
22 published journal articles · 1 journal discussion contribution · 2 accepted papers · 2 conference proceedings papers · 2 book chapters
Journal articles
2026
1. Sun, J., Cole, M., & Härdle, W. K. (2026). "Using Machine Learning for Prediction and Policy Analysis in Economics." The Review of Mathematical Economics, 1(2), 235–276. https://doi.org/10.4310/RME.260730231155
2. Yao, J., Wu, J., Feng, H., & Sun, J. (2026). "Supply Chain Shocks and the Reconfiguration of Green Finance Markets: A Quantile-on-Quantile Connectedness Analysis." Systems, 14(6), 652. https://doi.org/10.3390/systems14060652
3. Jiang, W., Sun, J., Cole, M., & Zhang, Y. (2026). "Virtual water in global supply chains: Trade structure, industrial composition, and policy levers." Ecological Economics, 248, 109068. https://doi.org/10.1016/j.ecolecon.2026.109068
4. Wu, J., Yao, J., & Sun, J. (2026). "Risk Propagation and System Resilience in Sustainable-Digital Finance: A Time-Frequency Higher-Order Moment Analysis of Green Finance, Green Cryptocurrency, and Non-Green Cryptocurrency Markets." Systems, 14(6), 628. https://doi.org/10.3390/systems14060628
5. Wu, J., Sun, J., Feng, H., & Long, F. (2026). "Stablecoins, Risk Transmission and Systemic Reconfiguration in a Fragmented USD Access System: Evidence from Quantile Time-Frequency Analysis." Systems, 14(5), 562. https://doi.org/10.3390/systems14050562
6. Chen, X., Liu, J., Sun, J., Zhang, Q., Yan, X., & Long, F. (2026). "Mathematical sciences for trustworthy AI corpora." Data Analytics and Topology, 2(1), 53–84. https://doi.org/10.4310/dat.260923131244
2025
7. Sun, J., Zhu, M., & Linton, O. (2025). "Adjusted-range-based self-normalized autocorrelation tests." Economics Letters, 251, 112315. https://doi.org/10.1016/j.econlet.2025.112315
8. Sun, J., Hong, Y., Lin, Z., & Xu, W. (2025). "Structural stability of functional data: A new adjusted-range-based self-normalization approach." Economics Letters, 253, 112350. https://doi.org/10.1016/j.econlet.2025.112350
9. Cole, M., Sun, J., Jiang, W., & Zang, L. (2025). "Governmental Capabilities and Responsiveness: Global Investigations into CO2 Emissions and Decarbonization. The Ultimate Super Wicked Problem!" International Journal of Public Administration, 48(8), 532–550. https://doi.org/10.1080/01900692.2024.2386271
2024
10. Hong, Y., Linton, O., McCabe, B., Sun, J., & Wang, S. (2024). "Kolmogorov-Smirnov type testing for structural breaks: A new adjusted-range-based self-normalization approach." Journal of Econometrics, 238(2), 105603. https://doi.org/10.1016/j.jeconom.2023.105603
2022
11. Shao, C., Guan, X., Sun, J., Cole, M., & Liu, G. (2022). "Social media interactions between government and the public: A Chinese case study of government WeChat official accounts on information related to COVID-19." Frontiers in Psychology, 13, 955376. https://doi.org/10.3389/fpsyg.2022.955376
12. Jiang, W., Cole, M., Sun, J., & Wang, S. (2022). "Innovation, carbon emissions, and the pollution haven hypothesis: Climate capitalism and global reinterpretations." Journal of Environmental Management, 307, 114465. https://doi.org/10.1016/j.jenvman.2022.114465
13. Hong, Y., Linton, O., McCabe, B., & Sun, J. (2022). "A score statistic for testing the presence of a stochastic trend in conditional variances." Economics Letters, 213, 110394. https://doi.org/10.1016/j.econlet.2022.110394
14. Sun, J., Hong, Y., Linton, O., & Zhao, X. (2022). "Adjusted-range self-normalized confidence interval construction for censored dependent data." Economics Letters, 110873. https://doi.org/10.1016/j.econlet.2022.110873
15. Hong, Y., Sun, J., McCabe, B., & Wang, S. (2022). 基于调整样本值域的自正则结构性变化的检验 [An adjusted-range based self-normalized statistic for testing structural breaks]. 统计研究 (Statistical Research), 39(4), 122–133. https://doi.org/10.19343/j.cnki.11-1302/c.2022.04.009
2020
16. Sun, J., McCabe, B., Cui, W., & Li, G. (2020). 基于Katz分布的计数数据自回归模型以及其在预测呼吸系统患病人数中的应用 [Integer-valued autoregressive processes with Katz arrivals and their application to respiratory disease counts]. 应用概率统计 (Chinese Journal of Applied Probability and Statistics), 36(6), 551–568.
2019
17. Sun, J., Cole, M., Huang, Z., & Wang, S. (2019). "Chinese leadership: Provincial perspectives on promotion and performance." Environment and Planning C: Politics and Space, 37(4), 750-772. https://doi.org/10.1177/2399654418791580
2018
18. Cui, W., Cheng, H., & Sun, J. (2018). "An RKHS-based approach to double-penalized regression in high-dimensional partially linear models." Journal of Multivariate Analysis, 168, 201-210. https://doi.org/10.1016/j.jmva.2018.07.013
2013
19. Li, Z., Sun, J., & Wang, S. (2013). "An information diffusion-based model of oil futures price." Energy Economics, 36, 518-525. https://doi.org/10.1016/j.eneco.2012.10.009
20. Sun, Jiajing, and Brendan P. McCabe. “Score Statistics for Testing Serial Dependence in Count Data.” Journal of Time Series Analysis 34, no. 3 (2013): 315–329. https://doi.org/10.1111/jtsa.12014
2011
21. Gunter, Lacey, Michael R. Chernick, and Jiajing Sun. “A Simple Method for Variable Selection in Regression with Respect to Treatment Selection.” Pakistan Journal of Statistics and Operation Research 7, no. 2-Sp (2011): 363–380. https://doi.org/10.18187/pjsor.v7i2-Sp.311
22. Sun, J., Chernick, M. R., & LaBudde, R. A. (2011). "A bootstrap test for comparing two variances: simulation of size and power in small samples." Journal of Biopharmaceutical Statistics, 21(6), 1079-1093. https://doi.org/10.1080/10543406.2011.611082
Journal discussion contribution
Hong, Y., Linton, O., Sun, J., & Zhu, M. (2024). Contribution to the Discussion of “the Discussion Meeting on Probabilistic and statistical aspects of machine learning”. Journal of the Royal Statistical Society Series B: Statistical Methodology, 86(2), 320–321. https://doi.org/10.1093/jrsssb/qkad152
Accepted for publication
1. Wu, Junda, Qiqi Gu, Jian Yao, and Jiajing Sun. “Defining and Monitoring Stablecoin Depegging Risk: A Rolling Downside-Threshold Framework.” Digital Finance. Accepted. Corresponding author: Jiajing Sun.
2. 孙佳婧、林卓、Brendan McCabe. 带协变量的计数数据自回归模型的模型平均 [Model Averaging for Count-Data Autoregressive Models with Covariates]. 计量经济学报 (China Journal of Econometrics). Accepted. First author: Jiajing Sun.
Conference proceedings papers
Tickle, A. J., Sun, J., Smith, J. S., & Wu, Q. H. (2008). Feasibility of a morphological forensic document recovery system for burnt documents on field programmable gate arrays (FPGA). Proceedings of SPIE, 6978. https://doi.org/10.1117/12.777391
Tickle, A. J., Sun, J., Gan, L., & Smith, J. S. (2008). Feasibility of an encryption and decryption system for messages and images using a Field Programmable Gate Array (FPGA) as the portable encryption key platform. Proceedings of SPIE, 7100, 71002N. https://doi.org/10.1117/12.797732
Book chapters
Li, Z., Sun, J., & Cole, M. (2015). Mechanisms and performance of Chinese bear markets and policy suggestions. In Li, Z., & Cheng, S. (Eds.), The Chinese Stock Market Volume II (pp. 125-189). Palgrave Macmillan, London, UK. Available at https://link.springer.com/chapter/10.1057/9781137464699_3
Li, Z., & Sun, J. (2015). Mechanisms and performance of Chinese bear markets and policy suggestions. In Li, Z., & Cheng, S. (Eds.), China's Stock Market Review and Outlook: 2002-2013. Science Press, Beijing, China.
Textbooks and companion websites
Financial Econometrics: Theory, Cases, and R — Jiajing Sun, Yongmiao Hong and Oliver Linton. Chinese-language textbook. Lecture slides, videos and practice in R and Python
Econometrics and Time Series Methods: Theory, Applications, and R Implementation — Yongmiao Hong, Oliver Linton and Jiajing Sun. Chapter guides and time series resources
FinTech (金融科技学) — Jiajing Sun, Youwei Yang, Yongmiao Hong and Shouyang Wang. Chinese-language textbook. ISBN 978-7-04-068306-6. FinTech companion website
Regression with R and Python: Description, Prediction, and Causal Analysis in Social Science and Medicine — Per Johansson and Jiajing Sun. Forthcoming from Springer in 2027. Lecture materials, code and course resources · Springer book page
Applied Econometrics (应用计量经济学) — Jiajing Sun and Per Johansson. Chinese-language course and companion materials. Chapter videos and practical exercises in R and Python
Conferences
- Renmin University of China, April 18, 2025, Beijing, China, “Sequential change-point detection in time series: An adjusted-range-based self-normalization approach,” invited seminar presentation.
- University of Leicester, March 19, 2025, Leicester, UK, “Sequential change-point detection in time series: An adjusted-range-based self-normalization approach,” invited seminar presentation.
- BIMSA Digital Economy Lab Seminar, December 9, 2024, Beijing, China, “Confidence interval estimation and hypothesis testing using the adjusted-range self-normalization approach,” invited seminar presentation.
- 75th European Meeting of the Econometric Society, August 29, 2024, Rotterdam, Netherlands, “Confidence interval construction based on the adjusted-range self-normalization approach,” session presentation.
- 2024 Asian Meeting of the Econometric Society, June 28, 2024, Hangzhou, China, “Sequential change point detection for time series – an adjusted-range based approach,” session presentation.
- Gregory C. Chow’s Young Scholar Forum, April 18, 2022, Beijing, China, “Kolmogorov-Smirnov type testing for structural breaks: A new adjusted-range based self-normalization approach,” invited speech.
- CFE-CMStatistics, December 18-20, 2021, London, UK, “Confidence interval construction - a new self-normalization approach based on adjusted-range,” online presentation.
- Tsinghua University Statistics and Data Science Young Scholar Forum, October 23-24, 2021, Beijing, China, “Confidence interval construction - a new self-normalization approach based on adjusted-range,” session presentation.
- Australian Meeting of the Econometric Society, July 7-9, 2021, University of Melbourne, Melbourne, Australia, “Testing for structural breaks - a new self-normalization approach based on the adjusted sample range,” online presentation.
- Thirteenth Annual SoFiE Conference (North America), June 15-17, 2021, Rady School of Management at the University of California, San Diego, USA, “A score statistic on testing the presence of stochastic trends in conditional variance,” online presentation.
- 2021 North American Summer Meeting of the Econometric Society, June 13-19, 2021, Université du Québec à Montréal, Montreal, Canada, “Testing for structural breaks - a new self-normalization approach based on the adjusted sample range,” online presentation.
- 13th International Conference of the ERCIM WG on Computational and Methodological Statistics - 14th International Conference on Computational and Financial Econometrics, December 19-21, 2021, London, UK, “Testing structural breaks - a new self-normalization approach based on the adjusted sample range,” online presentation.
- Young Scholars Forum, April 23, 2021, School of Economics and Management, University of Chinese Academy of Sciences (UCAS), Beijing, China, “Kolmogorov-Smirnov type testing for structural breaks: A new adjusted-range based self-normalization approach,” session presentation.
- The 4th China Econometricians Forum, December 19-20, 2020, Shanghai Academy of Social Sciences, Shanghai, China, “Testing structural breaks - a new self-normalization approach based on the adjusted sample range,” session presentation.
- 12th Econometric Society World Congress, August 17-21, 2020, Milan, Italy, “Model averaging of integer-valued autoregressive model with covariates,” online presentation.
- 2019 Asian Meeting of the Econometric Society, June 14-16, 2019, Xiamen University, China, “Model averaging of integer-valued autoregressive model with covariates,” session presentation.
- CES (China Economic Society), June 8-9, 2019, annual conference, Dongbei University of Finance and Economics, Dalian, China, “The subjective well-being of internal migrants: lessons from China,” session presentation.
- 9th ERCIM WG on Computational and Methodological Statistics; 10th International Conference on Computational and Financial Econometrics, December 9, 2016, University of Seville, Spain, “RKHS-based approach to SCAD-penalized regression in high-dimensional partially linear models,” session presentation.
- IEEE Symposium on Analytics and Risk, August 14, 2015, University of Chinese Academy of Sciences, Beijing, China, “Commodity shocks and the macroeconomy,” session presentation.
Student Supervision
Current master’s students
Zhang Xi (张晰) — Finance (academic master’s programme)
Du Yifei (杜逸飞) — Finance (professional master’s programme)
Lü Xuejie (吕雪杰) — Business Administration (MBA)
Qin Mu (秦沐) — Business Administration (MBA)
Wang Bei (王蓓) — Business Administration (MBA)
Zhang Yajing (张雅婧) — Business Administration (MBA)
Hu Yue (胡玥) — Business Administration (MBA)
Chen Zhongtao (陈忠涛) — Business Administration (MBA)
Yan Jiapeng (严加鹏) — Business Administration (MBA)
Shi Zhaobo (史兆博) — Business Administration (MBA)
Former master’s students
Cao Songfei (曹松飞) — Business Administration (MBA)
Li Jiamin (李佳敏) — Management Science and Engineering
Wu Junda (吾俊达) — Finance (academic master’s programme)
Cao Zhong (曹中) — Business Administration (MBA)
Liu Xin (刘欣) — Finance (professional master’s programme)
Wang Weiguang (王伟光) — Finance (professional master’s programme)
Shi Can (石灿) — Business Administration (MBA)
Xu Yang (徐杨) — Quantitative Economics
Zhang Zijing (张紫靖) — Quantitative Economics
Yu Gaoqi (余高麒) — Business Administration (MBA)
Wang Lei (王磊) — Business Administration (MBA)
Han Yupei (韩雨沛) — Quantitative Economics
Xu Xinyi (徐心怡) — Finance (professional master’s programme)
Du Chenxi (杜晨曦) — Business Administration (MBA)
Yuan Zhen (袁震) — Business Administration (MBA)
Ren Jinxuan (任津铉) — Business Administration (MBA)
Sun Jianyi (孙健益) — Business Administration (MBA)
Selected student achievements
Wu Junda received Outstanding Youth League Member and Excellent Student honours before pursuing doctoral study at the Beijing Institute of Mathematical Sciences and Applications. Xu Yang received student leadership honours and served as President of the Student Union in the School of Economics and Management.
During her master’s studies, Zhang Zijing received an Excellent Student award and first prize in the 2023 Popular Science & Science Fiction Contest. She served as deputy class monitor and helped her class earn a UCAS May Fourth Red Flag Youth League Branch award in 2023–2024.
Li Jiamin went on to doctoral study at Renmin University of China. After graduation, Cao Songfei founded Shanxi Yimiao Supply Chain Management Co., Ltd.
Collaborative supervision and mentorship
Dr Sun co-organises the School’s Econometrics Seminar Series with Professor Yongmiao Hong and collaborates with him in the supervision of master’s and doctoral students.
Honors & Distinctions
- The course "Financial Statistics and Econometrics" won the Young Teacher Teaching Special Award from the School of Management for the 2017-18 academic year and the Excellent Postgraduate Course Award in 2019.
- The course "Financial Data Modeling and Analysis" received the Excellent Postgraduate Course Award for the year 2022.
- In May 2023, Dr. Jiajing Sun was awarded the Third Prize in the Young Teacher's Basic Teaching Skills Competition.
Research Grants
- "Adjusted Range-Based Self-normalization in Time Series Analysis", Principal Investigator, NSFC Project, January 2022 - December 2025.
- "Economic Theories and Empirical Research on Employment, Subjective Well-being, Public Service Satisfaction, and Labor Market Efficiency in Major Chinese Cities", Principal Investigator, Chinese Academy of Sciences Program, January 2019 - December 2020.
- "Sparse Parameter Models in Big Data", Principal Investigator, Chinese Academy of Sciences Program, September 2015 - December 2017.
- "Spatial Integer-Valued Autoregressive Moving Average Models and Their Application in Socio-Economic Analysis", Principal Investigator, NSFC Project, January 2015 - December 2017.
- "Basic Research on Financial Futures Market Monitoring and Early Warning from the Perspective of Major Asset Classes", Participant, Domestic Commissioned Project, January 2018 - December 2018.
- "Investor Sentiment and Stock Market Policy Failure: Analysis and Empirical Evidence Based on Internet Big Data", Participant, NSFC Project, January 2017 - December 2020.
- "Nonlinear Mixed Frequency Data Models and Their Application in Economics", Participant, Ministry of Education, January 2015 - December 2017.
- "Risk Assessment and Optimization of Emergency Material Distribution Systems Under Sudden Natural Disasters", Participant, NSFC Project, January 2015 - December 2017.