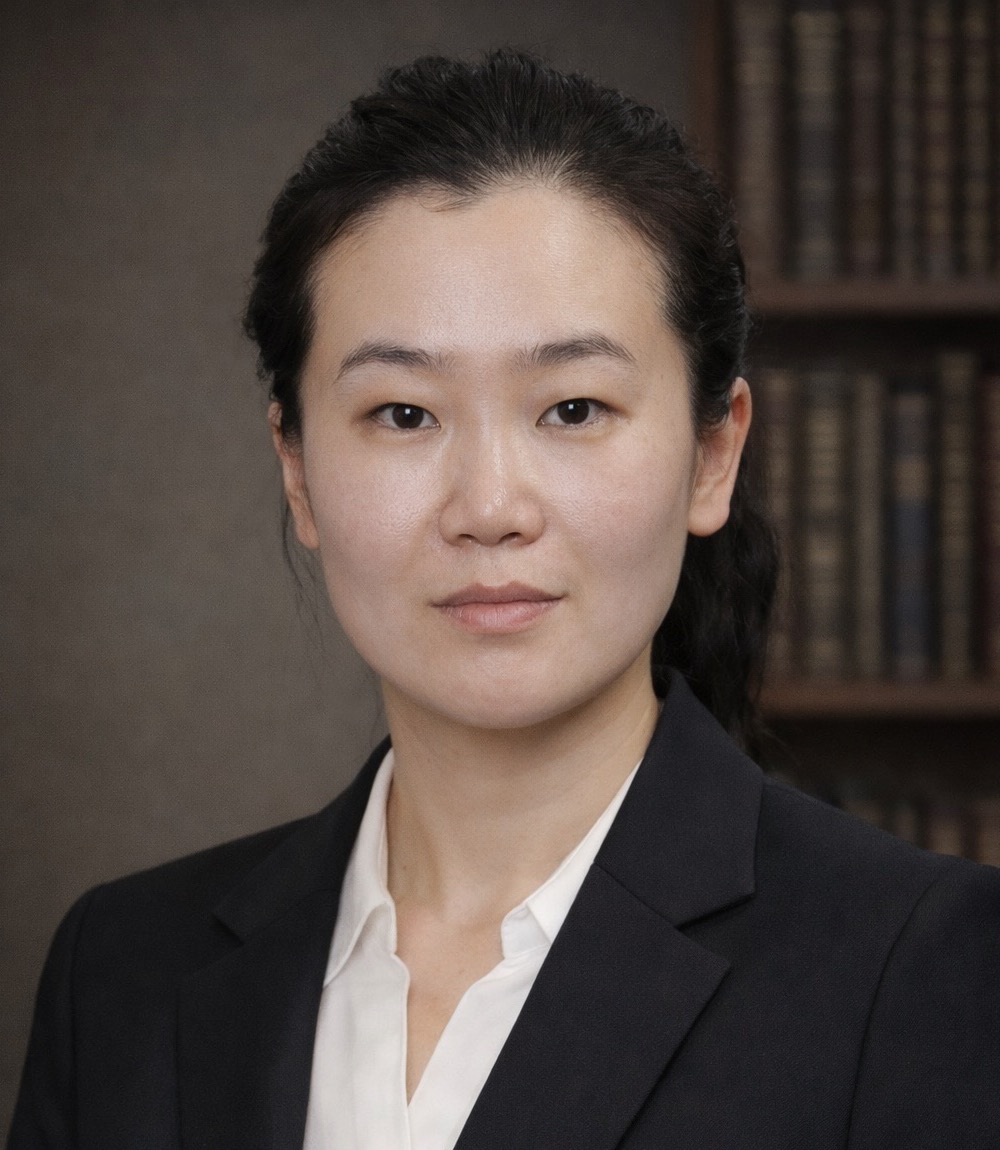
孙佳婧,中国科学院大学经济与管理学院副教授,统计与数据科学系副主任、教研室副主任。英国利物浦大学管理学博士(计量经济学),特许金融分析师(CFA),英国数学及其应用学会会士(FIMA)。研究方向为金融计量经济学、时间序列分析与风险监测。
期刊任职与专业学会
期刊副主编(Associate Editor) · The Review of Mathematical Economics · Digital Finance · Management & Marketing
数字资产研究所(Institute for Digital Assets (IDA))成员;英国数学及其应用学会(Institute of Mathematics and its Applications)会士(FIMA);伦敦数学学会(London Mathematical Society)会员。CFA 持证人凭证
研究与软件 | 仿射同变的调整值域自正则化
当研究者改变计量单位、重排系数或转换坐标时,对同一组经济参数的联合推断应当保持一致。孙佳婧与洪永淼、林卓、Oliver Linton、Whitney K. Newey 合作提出一种多元时间序列方法,无需估计长期协方差矩阵或选择带宽即可构造联合置信域。论文以美国财政乘数的联合推断为例,发表于剑桥大学 Janeway Institute 工作论文系列(第 2637 号)。
孙佳婧是配套软件包 aersn 的共同作者和维护者。R 与 Python 用户均可使用该方法。
剑桥工作论文 · R 包(CRAN) · Python 包(PyPI) · 方法与置信域动画
行业交流与公共评论
2026年10月29日,孙佳婧受邀在北京举行的第九届 CFA Institute 中国投资峰会主持圆桌讨论“科技投资:价值重估还是过度投资?”。来自投资管理、科技企业和学术界的嘉宾共同讨论了如何判断科技企业的估值,以及在行业快速扩张时如何识别过度投资。此前,她还就中国资本市场改革和清洁能源转型为 CFA Institute 提供专家评论,讨论公司治理与长期投资回报,以及为什么清洁能源行业的增长未必带来同等幅度的投资回报。
研究与应用
孙佳婧研究如何从持续更新的观测数据中识别经济关系的变化。她与合作者发展了基于调整样本值域的自正则推断方法,用于检验时间序列的结构突变和函数型数据的稳定性,并研究如何在线监测期权市场的风险信号。相关成果发表于 Journal of Econometrics、Economics Letters 和《统计研究》等期刊。她主持过多项国家自然科学基金项目,包括面上项目“基于调整样本值域的自正则时间序列分析”。
在金融监管与数字金融领域,她与中国金融期货交易所合作开展衍生品市场风险预警研究,并与团队一起利用文本分析和机器学习评估中国541家中小银行的数字金融竞争力。在生态经济学领域,她与合作者追踪全球供应链中的虚拟水流动,分别考察生产对雨水的利用、对地表水和地下水的取用,以及水污染带来的环境压力。相关成果发表于 Ecological Economics。
研究生教学与学术服务
孙佳婧将时间序列推断与真实金融数据结合,组织学生用 R 和 Python 复现模型、比较预测结果。《金融统计与计量经济学》获学院青年教师教学特别奖及2019年研究生优秀课程奖,《金融数据的建模与分析》获2022年研究生优秀课程奖。2026年7月,她参加哈佛商学院以参与者为中心的学习教学研讨项目。她也参与编写金融计量、时间序列、金融科技及回归分析方面的教材,配套网站公开分章讲义、视频和编程练习。
她曾任学院国际合作办公室副主任,负责筹备2022年和2023年亚洲计量经济学与统计学暑期学校,并参与2026年暑期学校的组织工作。
个人学术网站:https://jiajing-sun.com/
电子邮件:jiajing@ucas.ac.cn
通信地址:北京市海淀区中关村南一条中国科学院大学教学楼,邮编100190。
研究领域
金融计量与时间序列:从识别历史突变到实时监测
经济关系何时发生了变化?在异常信号刚刚出现时,又有多少证据足以判断原有模型已经失效?孙佳婧与合作者围绕这两个问题,发展了基于调整样本值域的自正则推断方法,以序列自身的波动构造检验尺度,减少推断对长期方差估计和带宽选择的依赖。这一研究从标量时间序列中的结构突变和自相关检验,延伸到整条曲线随时间演变的函数型数据。她主持国家自然科学基金面上项目“基于调整样本值域的自正则时间序列分析”,并以通讯作者身份在 Journal of Econometrics 发表结构突变检验研究,以第一作者身份在 Economics Letters 发表函数型数据结构稳定性研究。
结构突变检验 · Journal of Econometrics 函数型数据的结构稳定性 · Economics Letters
金融风险与数字金融:把市场信号转化为可检验的预警指标
在与中国金融期货交易所合作的衍生品风险预警研究中,判断价格波动是否值得预警,是一个直接关系到误报与漏报的问题。围绕这一难题,孙佳婧与合作者研究如何利用比特币期权隐含波动率捕捉下行风险,以及如何区分稳定币价格的短暂偏离与持续脱锚。关于稳定币脱锚的论文已获 Digital Finance 接收,孙佳婧为通讯作者。在银行研究中,她与团队将金融文本分析和机器学习用于中国541家中小银行的数字金融竞争力评价;在绿色金融研究中,她与合作者考察供应链冲击在不同市场状态下如何传导至清洁能源股票、绿色债券和碳市场。
环境与生态经济:追踪全球供应链中的资源与环境成本
一国消费的商品可能在另一国消耗淡水、占用环境容量。孙佳婧与合作者利用覆盖189个国家、跨越2010—2021年的多区域投入产出数据,追踪国际贸易中的虚拟水流动。研究将雨水利用、地表水与地下水取用、水污染造成的压力分别核算,发现制造业在经济中所占比重与灰水净流出的关联最为突出。这一区分揭示了单一用水总量容易掩盖的问题:即使出口规模相近,不同产业结构的经济体也可能承担截然不同的水资源与污染负担。该研究发表于 Ecological Economics,孙佳婧为通讯作者。她的相关研究还考察技术创新、碳排放与污染避难所假说,成果发表于 Journal of Environmental Management。
招生信息
招生专业
教育背景
学历
英国利物浦大学管理学 博士
英国爱丁堡大学理学 硕士
天津财经大学经济学 本科 (三年完成本科学业)
特许金融分析师(CFA)
数学及其应用研究所会员 (Fellow of the Institute of Mathematics and its Applications,简称FIMA)
教师发展与案例教学
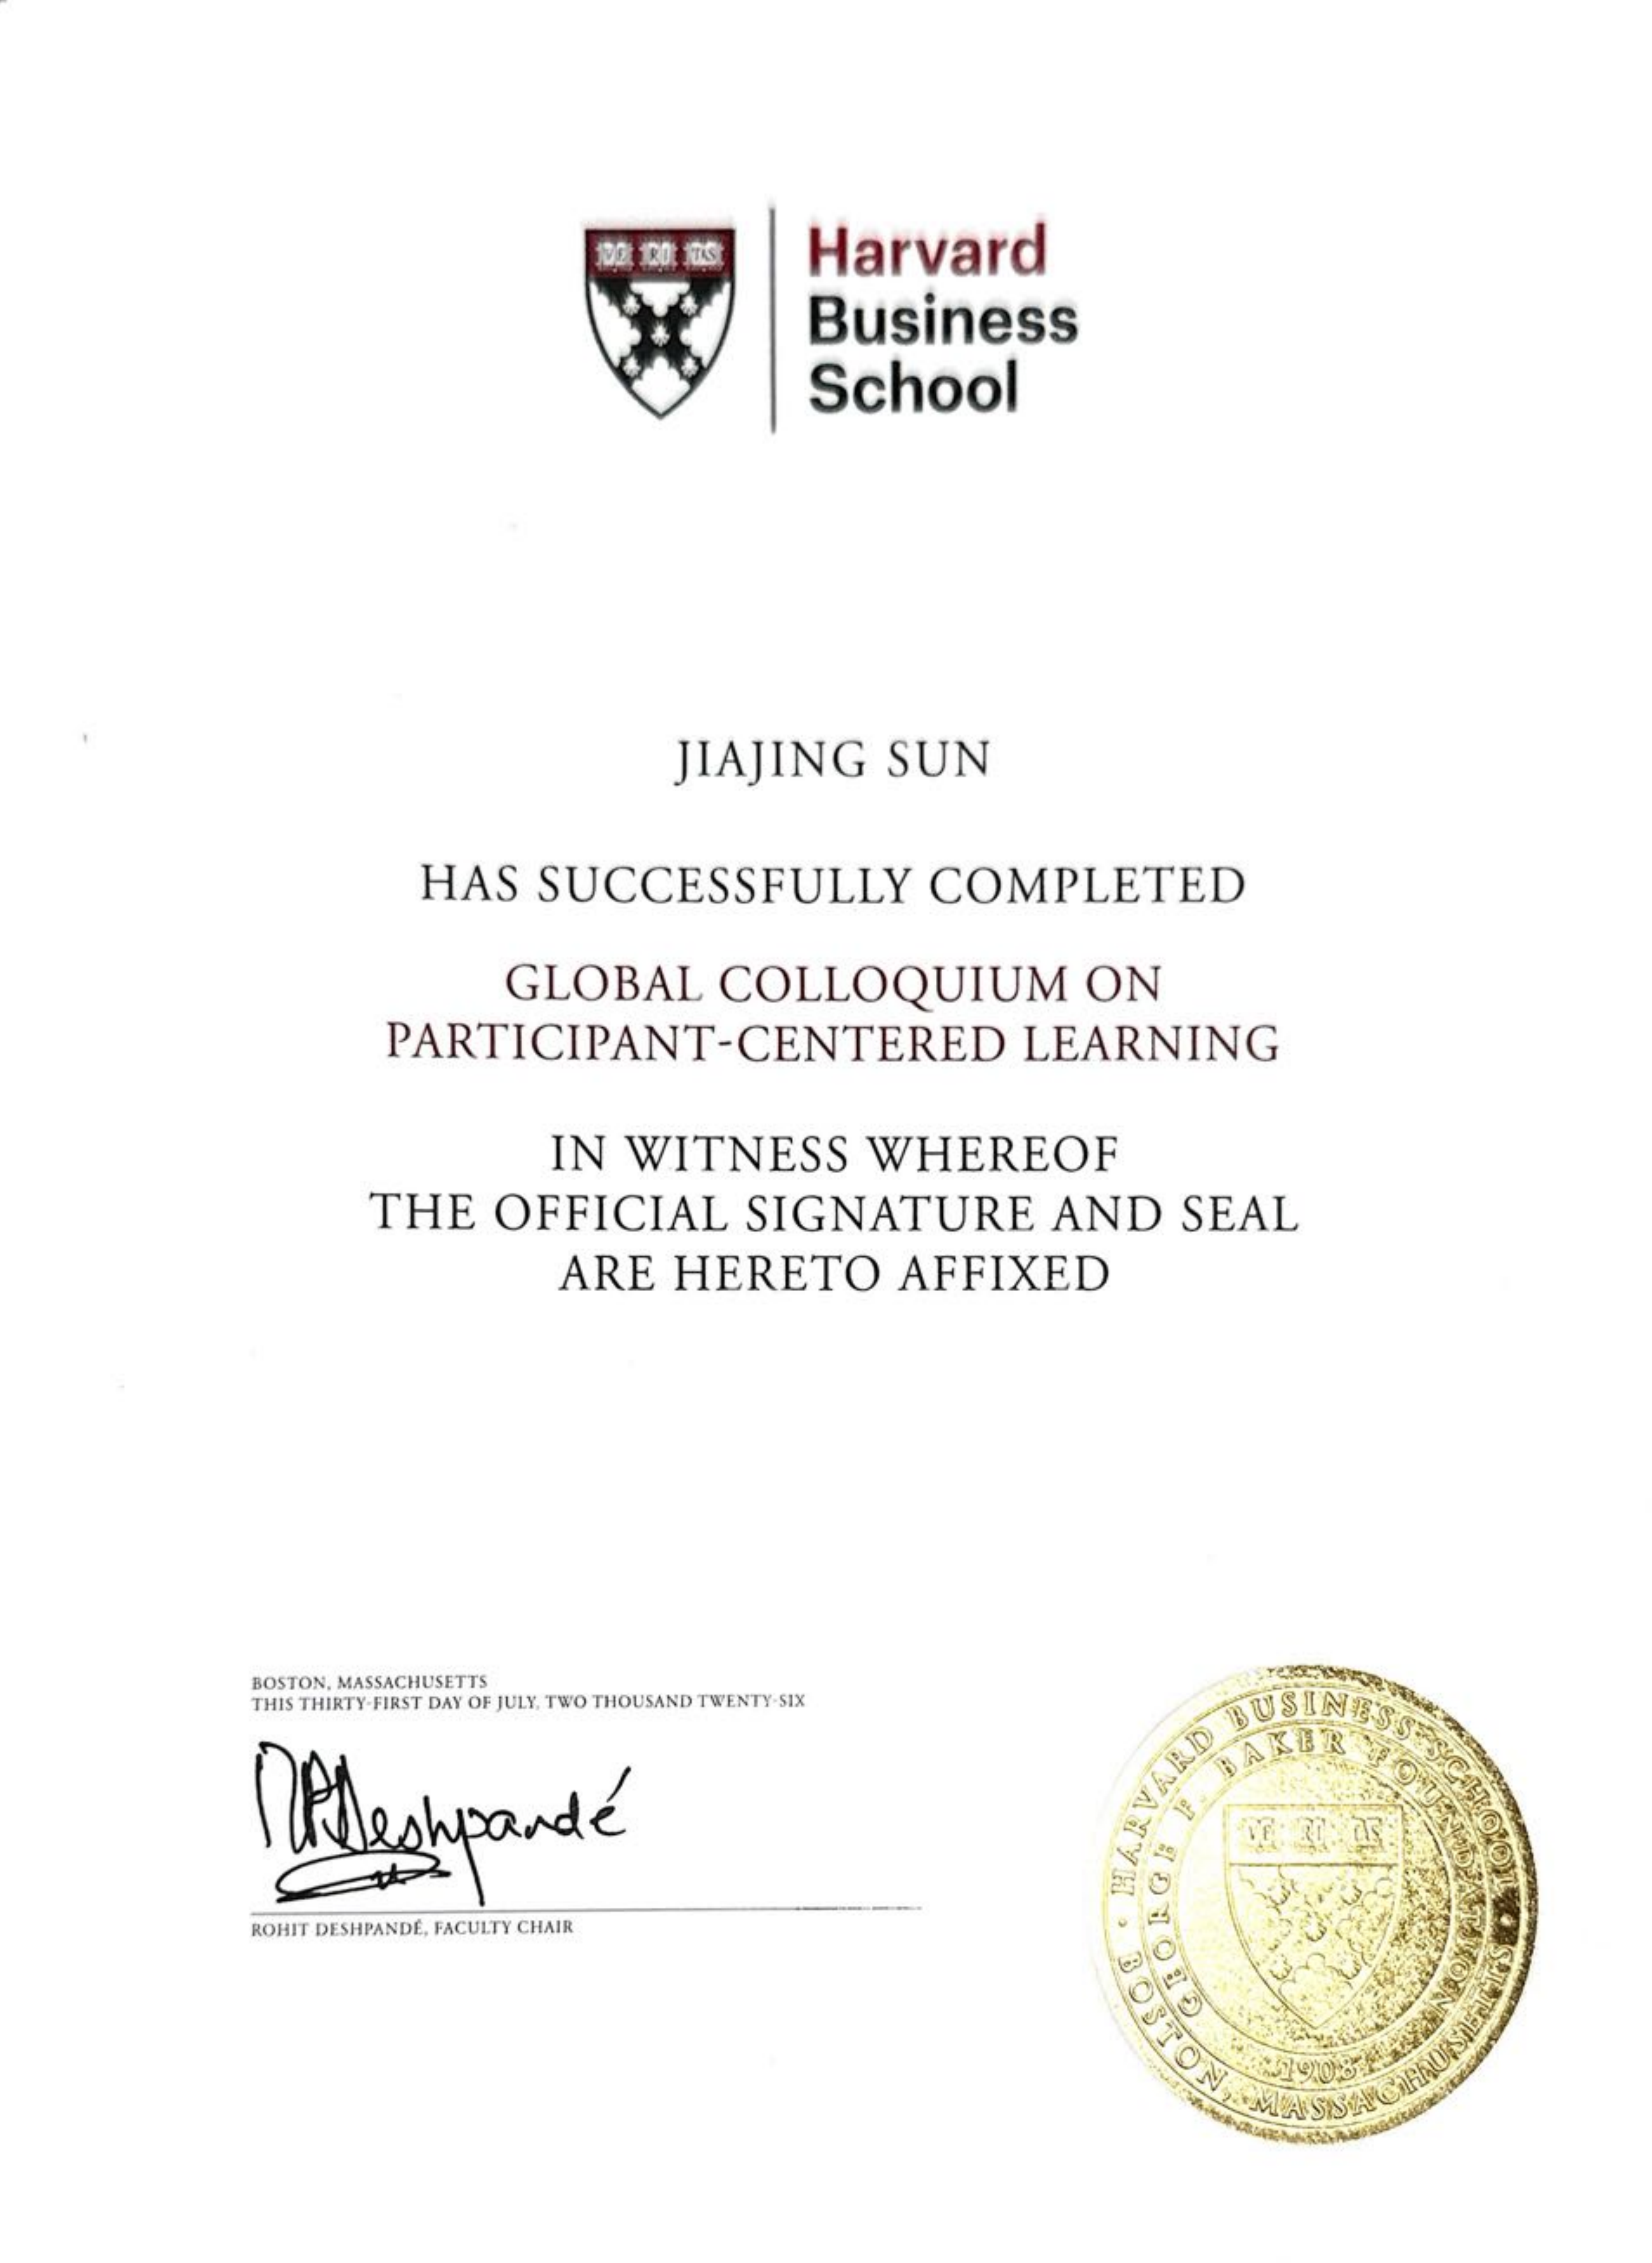
哈佛商学院 · Harvard Business School Executive Education|2026年7月26日至31日,美国波士顿。
参加 Global Colloquium on Participant-Centered Learning(以参与者为中心的学习研讨项目),围绕案例教学、课堂讨论引导、课程设计与案例开发开展研习。查看项目证书
学位
管理学博士、理学硕士、经济学学士。
教授课程
出版信息
论文与书籍章节|成果目录
已发表期刊论文 22 篇 · 期刊讨论文章 1 篇 · 已接收待刊 2 篇 · 会议论文 2 篇 · 书籍章节 2 篇
期刊论文
2026
1. Sun, J., Cole, M., & Härdle, W. K. (2026). "Using Machine Learning for Prediction and Policy Analysis in Economics." The Review of Mathematical Economics, 1(2), 235–276. https://doi.org/10.4310/RME.260730231155
2. Yao, J., Wu, J., Feng, H., & Sun, J. (2026). "Supply Chain Shocks and the Reconfiguration of Green Finance Markets: A Quantile-on-Quantile Connectedness Analysis." Systems, 14(6), 652. https://doi.org/10.3390/systems14060652
3. Jiang, W., Sun, J., Cole, M., & Zhang, Y. (2026). "Virtual water in global supply chains: Trade structure, industrial composition, and policy levers." Ecological Economics, 248, 109068. https://doi.org/10.1016/j.ecolecon.2026.109068
4. Wu, J., Yao, J., & Sun, J. (2026). "Risk Propagation and System Resilience in Sustainable-Digital Finance: A Time-Frequency Higher-Order Moment Analysis of Green Finance, Green Cryptocurrency, and Non-Green Cryptocurrency Markets." Systems, 14(6), 628. https://doi.org/10.3390/systems14060628
5. Wu, J., Sun, J., Feng, H., & Long, F. (2026). "Stablecoins, Risk Transmission and Systemic Reconfiguration in a Fragmented USD Access System: Evidence from Quantile Time-Frequency Analysis." Systems, 14(5), 562. https://doi.org/10.3390/systems14050562
6. Chen, X., Liu, J., Sun, J., Zhang, Q., Yan, X., & Long, F. (2026). "Mathematical sciences for trustworthy AI corpora." Data Analytics and Topology, 2(1), 53–84. https://doi.org/10.4310/dat.260923131244
2025
7. Sun, J., Zhu, M., & Linton, O. (2025). "Adjusted-range-based self-normalized autocorrelation tests." Economics Letters, 251, 112315. https://doi.org/10.1016/j.econlet.2025.112315
8. Sun, J., Hong, Y., Lin, Z., & Xu, W. (2025). "Structural stability of functional data: A new adjusted-range-based self-normalization approach." Economics Letters, 253, 112350. https://doi.org/10.1016/j.econlet.2025.112350
9. Cole, M., Sun, J., Jiang, W., & Zang, L. (2025). "Governmental Capabilities and Responsiveness: Global Investigations into CO2 Emissions and Decarbonization. The Ultimate Super Wicked Problem!" International Journal of Public Administration, 48(8), 532–550. https://doi.org/10.1080/01900692.2024.2386271
2024
10. Hong, Y., Linton, O., McCabe, B., Sun, J., & Wang, S. (2024). "Kolmogorov-Smirnov type testing for structural breaks: A new adjusted-range-based self-normalization approach." Journal of Econometrics, 238(2), 105603. https://doi.org/10.1016/j.jeconom.2023.105603
2022
11. Shao, C., Guan, X., Sun, J., Cole, M., & Liu, G. (2022). "Social media interactions between government and the public: A Chinese case study of government WeChat official accounts on information related to COVID-19." Frontiers in Psychology, 13, 955376. https://doi.org/10.3389/fpsyg.2022.955376
12. Jiang, W., Cole, M., Sun, J., & Wang, S. (2022). "Innovation, carbon emissions, and the pollution haven hypothesis: Climate capitalism and global reinterpretations." Journal of Environmental Management, 307, 114465. https://doi.org/10.1016/j.jenvman.2022.114465
13. Hong, Y., Linton, O., McCabe, B., & Sun, J. (2022). "A score statistic for testing the presence of a stochastic trend in conditional variances." Economics Letters, 213, 110394. https://doi.org/10.1016/j.econlet.2022.110394
14. Sun, J., Hong, Y., Linton, O., & Zhao, X. (2022). "Adjusted-range self-normalized confidence interval construction for censored dependent data." Economics Letters, 110873. https://doi.org/10.1016/j.econlet.2022.110873
15. Hong, Y., Sun, J., McCabe, B., & Wang, S. (2022). 基于调整样本值域的自正则结构性变化的检验 [An adjusted-range based self-normalized statistic for testing structural breaks]. 统计研究 (Statistical Research), 39(4), 122–133. https://doi.org/10.19343/j.cnki.11-1302/c.2022.04.009
2020
16. Sun, J., McCabe, B., Cui, W., & Li, G. (2020). 基于Katz分布的计数数据自回归模型以及其在预测呼吸系统患病人数中的应用 [Integer-valued autoregressive processes with Katz arrivals and their application to respiratory disease counts]. 应用概率统计 (Chinese Journal of Applied Probability and Statistics), 36(6), 551–568.
2019
17. Sun, J., Cole, M., Huang, Z., & Wang, S. (2019). "Chinese leadership: Provincial perspectives on promotion and performance." Environment and Planning C: Politics and Space, 37(4), 750-772. https://doi.org/10.1177/2399654418791580
2018
18. Cui, W., Cheng, H., & Sun, J. (2018). "An RKHS-based approach to double-penalized regression in high-dimensional partially linear models." Journal of Multivariate Analysis, 168, 201-210. https://doi.org/10.1016/j.jmva.2018.07.013
2013
19. Li, Z., Sun, J., & Wang, S. (2013). "An information diffusion-based model of oil futures price." Energy Economics, 36, 518-525. https://doi.org/10.1016/j.eneco.2012.10.009
20. Sun, Jiajing, and Brendan P. McCabe. “Score Statistics for Testing Serial Dependence in Count Data.” Journal of Time Series Analysis 34, no. 3 (2013): 315–329. https://doi.org/10.1111/jtsa.12014
2011
21. Gunter, Lacey, Michael R. Chernick, and Jiajing Sun. “A Simple Method for Variable Selection in Regression with Respect to Treatment Selection.” Pakistan Journal of Statistics and Operation Research 7, no. 2-Sp (2011): 363–380. https://doi.org/10.18187/pjsor.v7i2-Sp.311
22. Sun, J., Chernick, M. R., & LaBudde, R. A. (2011). "A bootstrap test for comparing two variances: simulation of size and power in small samples." Journal of Biopharmaceutical Statistics, 21(6), 1079-1093. https://doi.org/10.1080/10543406.2011.611082
期刊讨论文章
Hong, Y., Linton, O., Sun, J., & Zhu, M. (2024). Contribution to the Discussion of “the Discussion Meeting on Probabilistic and statistical aspects of machine learning”. Journal of the Royal Statistical Society Series B: Statistical Methodology, 86(2), 320–321. https://doi.org/10.1093/jrsssb/qkad152
已接收待刊
1. Wu, Junda, Qiqi Gu, Jian Yao, and Jiajing Sun. “Defining and Monitoring Stablecoin Depegging Risk: A Rolling Downside-Threshold Framework.” Digital Finance. 已接收;孙佳婧为通讯作者。
2. 孙佳婧、林卓、Brendan McCabe. 带协变量的计数数据自回归模型的模型平均 [Model Averaging for Count-Data Autoregressive Models with Covariates]. 计量经济学报 (China Journal of Econometrics). 已接收;孙佳婧为第一作者。
会议论文(正式收入论文集)
Tickle, A. J., Sun, J., Smith, J. S., & Wu, Q. H. (2008). Feasibility of a morphological forensic document recovery system for burnt documents on field programmable gate arrays (FPGA). Proceedings of SPIE, 6978. https://doi.org/10.1117/12.777391
Tickle, A. J., Sun, J., Gan, L., & Smith, J. S. (2008). Feasibility of an encryption and decryption system for messages and images using a Field Programmable Gate Array (FPGA) as the portable encryption key platform. Proceedings of SPIE, 7100, 71002N. https://doi.org/10.1117/12.797732
书籍章节
Li, Z., Sun, J., & Cole, M. (2015). Mechanisms and performance of Chinese bear markets and policy suggestions. In Li, Z., & Cheng, S. (Eds.), The Chinese Stock Market Volume II (pp. 125-189). Palgrave Macmillan, London, UK. Available at https://link.springer.com/chapter/10.1057/9781137464699_3
Li, Z., & Sun, J. (2015). Mechanisms and performance of Chinese bear markets and policy suggestions. In Li, Z., & Cheng, S. (Eds.), China's Stock Market Review and Outlook: 2002-2013. Science Press, Beijing, China.
教材与配套学习网站
金融计量经济学:理论、案例与 R — 孙佳婧、洪永淼、Oliver Linton。 讲义、教学视频与 R 和 Python 练习
Econometrics and Time Series Methods: Theory, Applications, and R Implementation — Yongmiao Hong、Oliver Linton、Jiajing Sun。 分章讲义与时间序列学习资料
金融科技学 — 孙佳婧、杨佑玮、洪永淼、汪寿阳。ISBN 978-7-04-068306-6。 教材配套网站
Regression with R and Python: Description, Prediction, and Causal Analysis in Social Science and Medicine — Per Johansson、孙佳婧。Springer,预计2027年出版。 讲义、代码与课程资源 · Springer 出版页
应用计量经济学 — 孙佳婧、Per Johansson。中文课程与教材配套资源。 章节视频与 R、Python 实践
指导学生
已指导学生
曹松飞 硕士研究生 125100-工商管理
李佳敏 硕士研究生 120100-管理科学与工程
吾俊达 硕士研究生 020204-金融学
曹中 硕士研究生 125100-工商管理
刘欣 硕士研究生 025100-金融
王伟光 硕士研究生 025100-金融
石灿 硕士研究生 125100-工商管理
徐杨 硕士研究生 020209-数量经济学
张紫靖 硕士研究生 020209-数量经济学
余高麒 硕士研究生 125100-工商管理
王磊 硕士研究生 125100-工商管理
韩雨沛 硕士研究生 020209-数量经济学
徐心怡 硕士研究生 025100-金融
杜晨曦 硕士研究生 125100-工商管理
袁震 硕士研究生 125100-工商管理
任津铉 硕士研究生 125100-工商管理
孙健益 硕士研究生 125100-工商管理
现指导学生
张晰 硕士研究生 020204-金融学
杜逸飞 硕士研究生 025100-金融
吕雪杰 硕士研究生 125100-工商管理
秦沐 硕士研究生 125100-工商管理
王蓓 硕士研究生 125100-工商管理
张雅婧 硕士研究生 125100-工商管理
胡玥 硕士研究生 125100-工商管理
陈忠涛 硕士研究生 125100-工商管理
严加鹏 硕士研究生 125100-工商管理
史兆博 硕士研究生 125100-工商管理